What is the scope and industry significance of the Cobblestone Market?
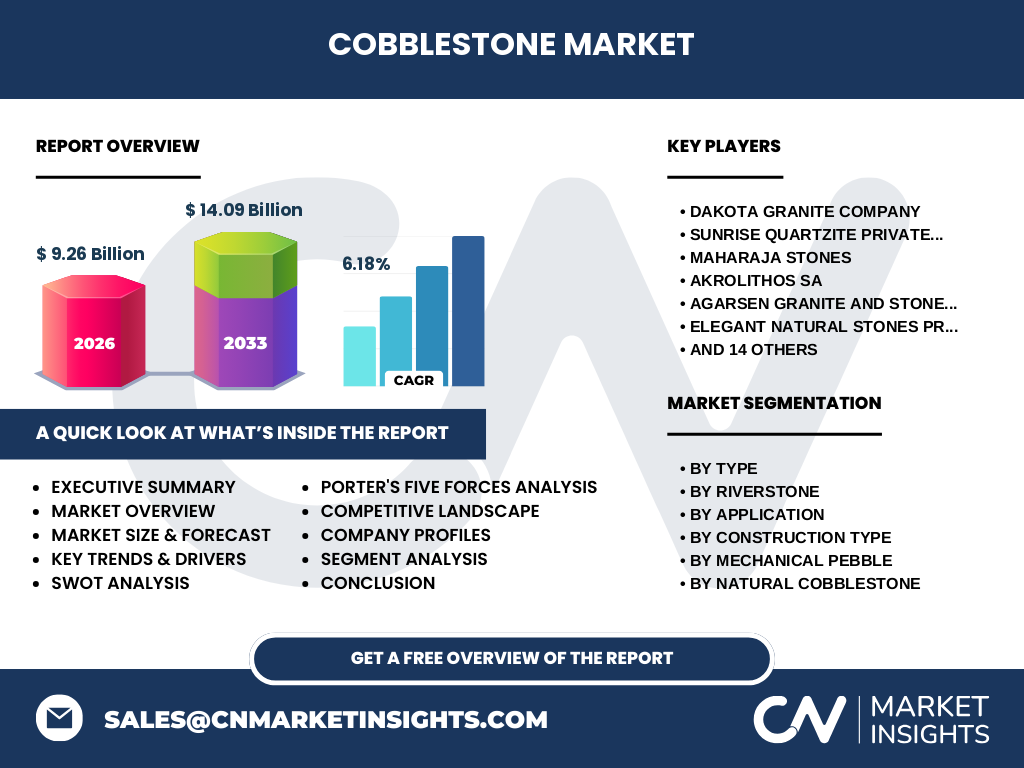
Our analysis indicates that the Cobblestone Market reaches a valuation of 9.26 Billion in 2026, driven by demand for durable mineral aggregates. This sector encompasses architectural masonry and heavy infrastructure, regulated by geological extraction standards and local environmental zoning laws governing quarries.
Structural Growth Drivers and Restraints
Growth is accelerated by urban pedestrianization initiatives favoring natural stone over asphalt. However, stringent EPA and EU quarrying restrictions create severe supply bottlenecks, forcing market participants to invest heavily in sustainable water recycling and waste reduction technologies during extraction.
Emerging Industry Trends and Regional Patterns
The shift toward bespoke architectural aesthetics has spiked demand for tumbled riverstone and basalt setts. Landscape architects increasingly specify textured surfaces to meet modern slip-resistance standards, directly influencing quarry production lines in Europe and North America.
Pandemic Impact and Macro Recovery
Supply chain disruptions during COVID-19 halted quarry operations and delayed maritime freight via major ports. Recovery has been robust, propelled by government-backed stimulus packages targeting civic infrastructure renovation and public space modernization across urban centers.
Competitive Benchmarking and Market Concentration
The landscape features a mix of global quarry giants and regional specialists. Polycor Incorporated and Levantina Group dominate through vertical integration, while niche players like Dakota Granite Company and Sunrise Quartzite Private Limited focus on specialized regional stone extraction.
Executive Summary of Cobblestone Market Insights
The Cobblestone Market is poised for steady expansion, underpinned by a projected valuation of 14.09 Billion by 2033. Stakeholders must navigate stringent environmental compliance while capitalizing on surging architectural renovation projects globally.
Long-Term Market Forecast and Projections
Driven by sustained infrastructure spending, our research projects the sector to expand at a Compound Annual Growth Rate (CAGR) of 6.18% from 2027 to 2033, culminating in a market size of 14.09 Billion by the end of the forecast period.
Segmentation Analysis Across Applications and Materials
The market divides by type into mechanical pebble, natural cobblestone, and riverstone. Natural cobblestone segments further into granite, basalt, limestone, and sandstone variants, catering to diverse structural load requirements in roading and architecture.
Geographic Distribution and Regional Performance
Regional demand correlates directly with historic urban preservation mandates and municipal paving budgets. European markets favor basalt and granite for heritage restorations, whereas North American projects frequently utilize regional limestone and manufactured mechanical pebbles.
In-Depth Regional Review of Key Markets
North America and Europe represent mature hubs governed by strict OSHA and MSHA safety guidelines. Meanwhile, Asia-Pacific exhibits aggressive volume growth, powered by rapid urbanization and large-scale commercial real estate developments demanding cost-effective mechanical pebbles.
Strategic Positioning of Leading Companies
Industry leaders leverage proprietary quarry access and advanced diamond-wire cutting technologies. Firms like Antolini Luigi and Company and Pokarna Limited focus on high-margin architectural slabs, while M S International Incorporated dominates high-volume distribution channels.
Porter's Five Forces Analysis
Supplier power remains moderate due to localized quarry monopolies, while the threat of substitutes is low given the unmatched durability of natural stone. Competitive rivalry is intense, compelling firms to optimize logistics through major regional distribution hubs.
SWOT Assessment of the Cobblestone Industry
Strengths lie in raw material longevity and timeless aesthetic appeal, contrasted by the weakness of high transportation costs. Opportunities abound in eco-certified permeable paving, while regulatory threats stem from carbon-emission caps on heavy stone crushing machinery.
Value Chain Analysis from Quarry to End-User
Value flows from raw block extraction at quarries through sawing, tumbling, and finishing phases. Logistical freight forwarding via rail and cargo ship bridges the gap between remote extraction sites and urban architectural distributors.
Investment Insights and High-Potential Areas
Investors should target automated tumbling facilities and quarries holding exclusive eco-certifications. Capitalizing on the renovation sector offers superior margin stability compared to highly competitive, bidding-heavy new construction projects.
Conclusion and Strategic Takeaways
Sustained by a 6.18% CAGR through 2033, the market rewards firms prioritizing environmental compliance and supply chain resilience. Adapting to green building codes will separate market leaders from legacy operators.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary interviews with quarry operators, and secondary macroeconomic indicators from global construction output indices to ensure absolute accuracy.
Scope of the Report and Analytical Limitations
This report covers global revenue streams from 2026 to 2033, focusing on primary stone extraction and secondary processing. Exclusions include synthetic resin-based imitation pavers and unregulated local quarrying activities lacking official trade data.
Recent Developments and Strategic Industry Moves
Recent market activity highlights major players investing in solar-powered crushing units to offset carbon taxes. Strategic mergers among regional suppliers aim to secure maritime shipping container allocations amidst ongoing global logistical fluctuations.